
International seat capacity in the United States declined by 2 per cent in Summer 2026, representing 4.6 million fewer seats compared with the corresponding period in 2025. However, the overall contraction masks contrasting trends across regions, with Africa and Asia Pacific recording growth as airlines continue to invest in new routes and expand existing services.
Data from aviation analytics firm OAG shows that Africa was the fastest-growing region in the US international market, with capacity increasing by 6 per cent, equivalent to an additional 107,000 seats. Asia Pacific also recorded a 2 per cent rise, adding 434,000 seats.
Together, the two regions contributed 541,000 additional seats, offsetting only a fraction of the reductions recorded elsewhere. The steepest decline came from the Middle East, where capacity fell by 16 per cent, while Latin America recorded a 4 per cent drop. Europe and North America each declined by 1 per cent.
The reductions in the Middle East and Latin America accounted for 97 per cent of the net capacity losses in the US international market, highlighting how developments in a few regions significantly influenced the overall performance.
Africa’s growth was largely driven by new route launches, particularly by Egyptair and Royal Air Maroc. Egyptair introduced two new services from Cairo to Los Angeles and Chicago, expanding its connectivity with the United States. The Chicago route, in particular, marked the realisation of a long-standing network expansion plan.
Royal Air Maroc also strengthened its transatlantic presence with the launch of a new Casablanca–Los Angeles service, opening a direct connection between its Moroccan hub and the US West Coast.
In Asia Pacific, United Airlines and Cathay Pacific were among the biggest contributors to capacity growth. United added 168,000 seats compared with Summer 2025, supported by the launch of a new Newark–Seoul service and additional capacity on routes connecting San Francisco with Manila, Tahiti and Tokyo, as well as services from Newark to Tokyo Narita and Los Angeles to Beijing Capital.
Cathay Pacific increased its US capacity by 167,000 seats, introducing a new Hong Kong–Seattle route and expanding services from Hong Kong to Dallas, Los Angeles, New York and Boston. The airline, however, reduced capacity on its San Francisco service.
Other carriers contributing to the expansion of the US–Asia Pacific market included Delta Air Lines, EVA Airways and Air Premia, each operating more than 100,000 additional seats compared with the previous summer.
The region also reflected the impact of airline consolidation. Alaska Airlines appeared in the US–Asia Pacific market for the first time following its merger with Hawaiian Airlines, effectively taking the place of the Hawaiian brand in the market.
The integration of Korean Air and Asiana Airlines also influenced capacity patterns. Although the Asiana brand is expected to be phased out in December 2026, the approved merger has already brought the two carriers together from a network perspective. Korean Air added 190,000 seats to the US market, while Asiana reduced its capacity by 124,000, resulting in a combined net increase of 66,000 seats.
The capacity reductions in North America and Europe were similarly concentrated among individual airlines rather than reflecting a broad-based decline in demand. In the North American market, WestJet cut 574,000 seats, representing a 17 per cent reduction from Summer 2025. Without the airline’s cuts, capacity from the rest of North America, largely Canada, to the United States would have increased by 377,000 seats, or 2 per cent.
Europe recorded a comparable pattern, with Norse Atlantic Airways reducing its capacity by 724,000 seats, a 62 per cent decline. Excluding the carrier’s reduction, European capacity to the US would have risen by 240,000 seats, or 0.4 per cent, indicating that demand for transatlantic travel remained relatively strong.
Among US carriers, United Airlines operated to the largest number of European destinations, serving 35 points during the summer season, ahead of Delta Air Lines, which served 28. Italy remained the leading European market for US airlines, with 17 routes operated by four carriers, followed by Spain with 12 routes and the United Kingdom with 10.
Looking ahead, United Airlines has already signalled further expansion for Summer 2027, announcing its largest-ever international network growth, including services to nine new European airports alongside additional expansion in Asia Pacific.
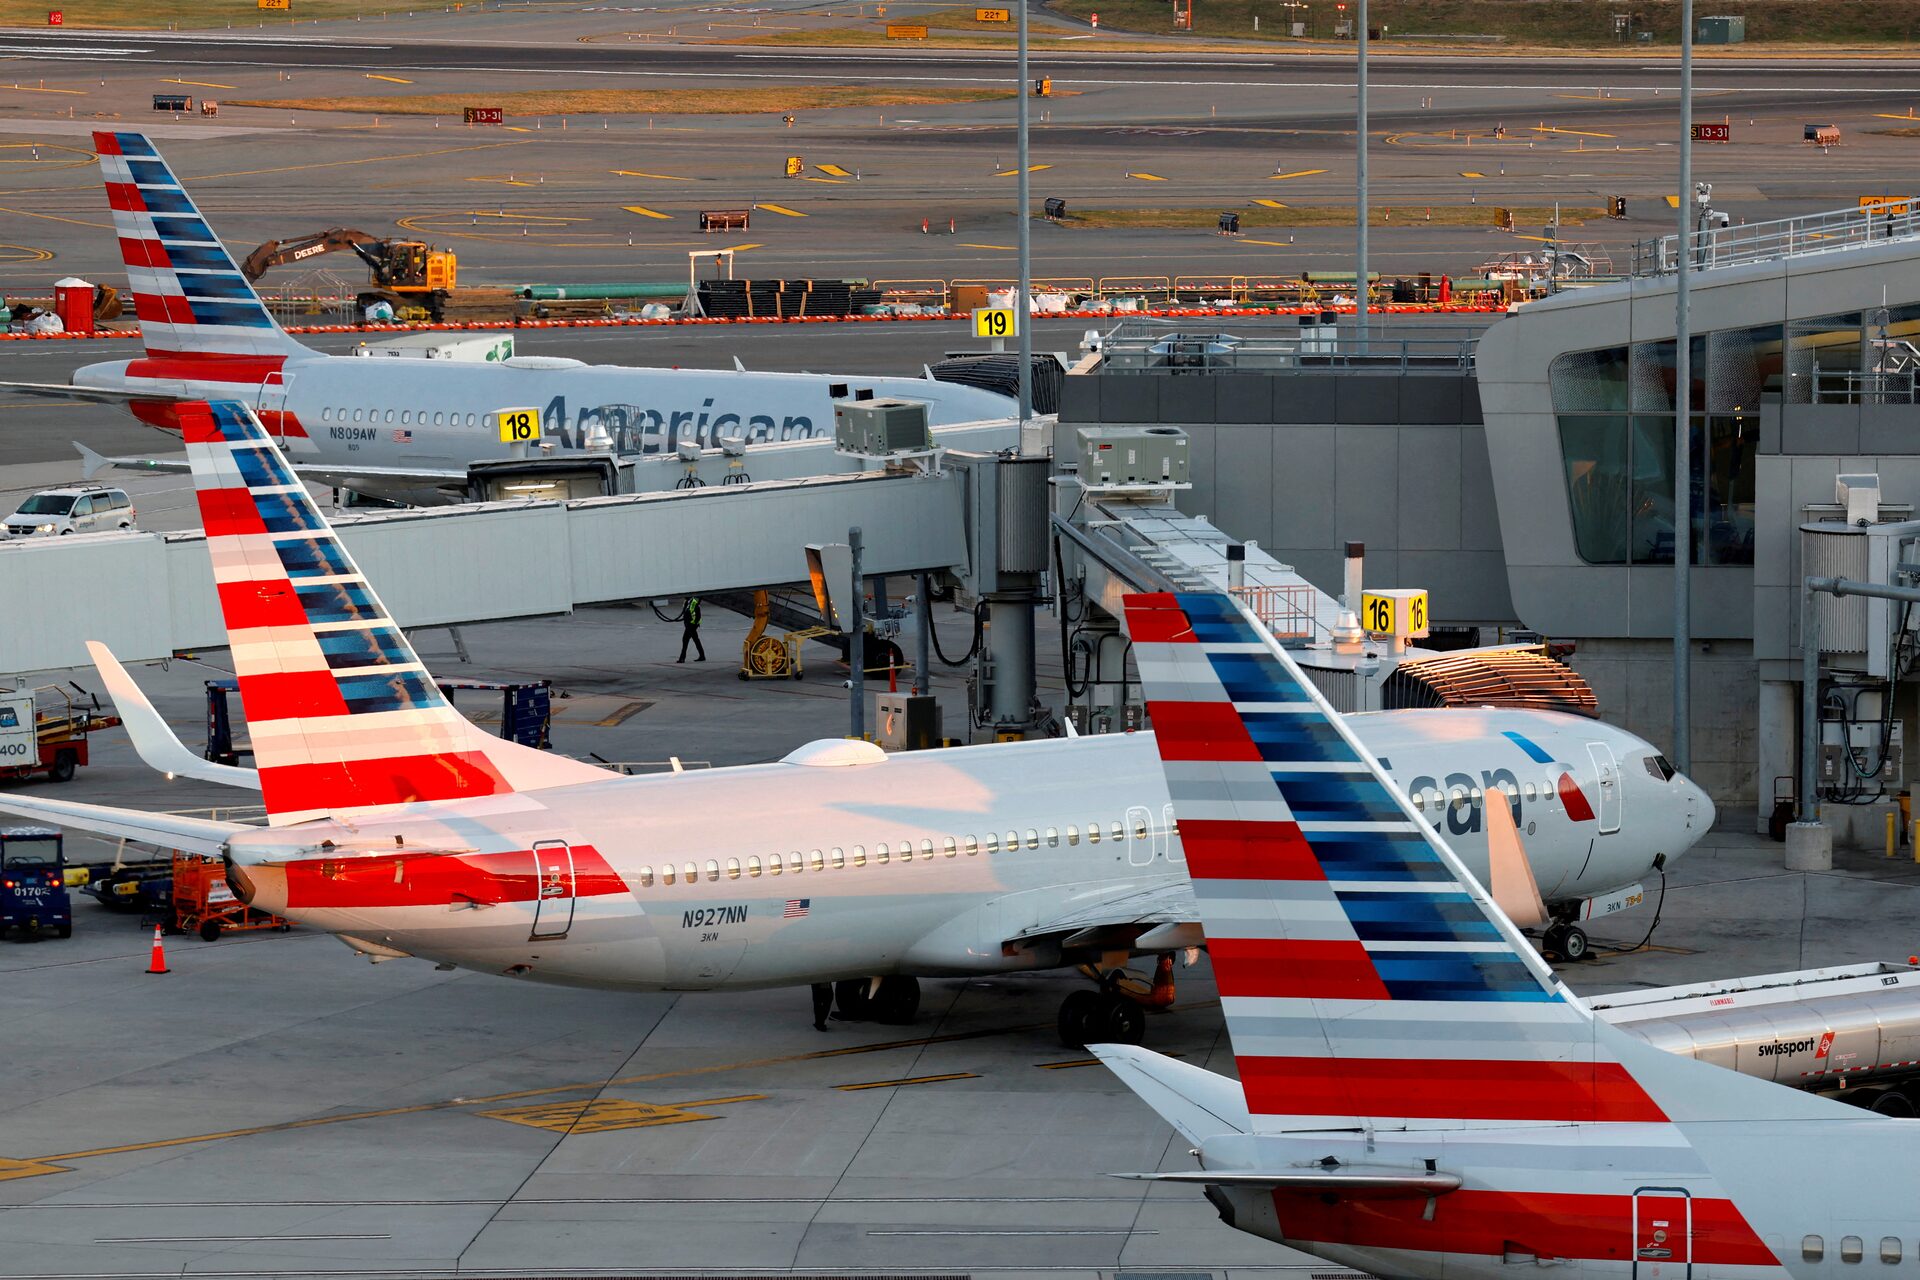
The broader question is whether Delta Air Lines, American Airlines and other US carriers will follow with comparable network investments, particularly as airlines continue to reassess capacity in response to demand, competition and changing market conditions.
The OAG figures suggest that, despite the overall decline in US international capacity, airlines are not retreating uniformly from overseas markets. Instead, new route launches, selective capacity increases and industry consolidation are reshaping the competitive landscape, with Africa and Asia Pacific emerging as the principal growth regions for the Summer 2026 season.